How is a Real Estate Syndication Divided in a Florida Divorce?
At a Glance
A real estate syndication cannot usually be split between spouses the way a bank account or a house can, so Florida divorces typically resolve it through a buyout, a deferred sharing arrangement, or an attempted private sale, depending on what the syndication’s own documents allow.
- Real estate syndications pool money from multiple investors to buy large properties, and most require investors to meet SEC accredited investor thresholds.
- These interests are hard to value and hard to sell, which shapes how they get divided in divorce.
- Common paths include a buyout, a constructive trust that shares a future payout, or a private sale attempt if the syndication’s agreement allows it.
- Collaborative Divorce lets you and your spouse design a solution around the syndication’s real restrictions, instead of asking a judge unfamiliar with the investment to decide for you.
Introduction – Real Estate Syndication Divided in Florida Divorce
If you have money tied up in a real estate syndication, you already know it does not behave like your other investments. You cannot log in and sell your shares this afternoon, and you cannot always find out what the interest is worth without hiring someone to dig into it. Now add a divorce to the picture, and a question that used to be background noise becomes urgent. What happens to that investment? Who keeps it? How do you make sure you get your share when the asset itself will not cooperate?
If you live in Tampa, St. Petersburg, Sarasota, or elsewhere in Florida and this describes your situation, you are not alone, and there is a path forward that does not require a judge who has never heard of a syndication deck to make the call for you.
What Is a Real Estate Syndication?
A real estate syndication is a group investment. A sponsor identifies a property, often an apartment complex, an office building, or a self storage facility, that may be too large for one investor to buy alone. The sponsor pools money from a group of investors, spreading the risk, then manages the property and distributes income and profits back to the group. Investors typically hold their stake through an LLC or limited partnership rather than owning the real estate directly.
For someone who has already built wealth through a medical practice, a law firm, a business, or an executive career, a syndication can be an appealing next step. It offers a way to diversify beyond stocks and bonds, access commercial properties that would otherwise be out of reach, and potentially benefit from depreciation and other tax advantages tied to real estate ownership. Some investors like that it is passive. Someone else runs the property, while you hold an ownership stake.
The tradeoffs are real, though. Returns are projections, not guarantees, and a downturn in a specific market or property type can affect the whole deal. Your money is usually locked up for a period of years with no early exit, and unlike a public stock, there is no ticker to check and no simple way to sell if your circumstances change. Anyone weighing one of these investments should hold the diversification and tax benefits up against that loss of control before committing marital or separate funds.
Who Can Invest, and Why That Matters in Divorce
Most syndications are only open to what the SEC calls accredited investors under Regulation D. Generally, according to a guide from Accountable Equity, that means an individual must have earned income over 200,000 dollars a year, or 300,000 dollars for a married couple, for the past two years, or have a net worth over 1 million dollars excluding a primary residence, according to SEC guidance describing accredited investors as anyone who earned income exceeding those thresholds in each of the prior two years with a reasonable expectation of the same, or who has a net worth over 1 million dollars excluding a primary residence. This threshold matters in divorce because it often means only one spouse holds the investor status and the relationship with the sponsor, even though both spouses may have a financial interest in the outcome.
Why These Interests Are Difficult to Value
Valuing a syndication interest is not as simple as pulling up an account balance. It is not publicly traded, so there is no daily price to point to. Its worth depends on the value of the underlying property, the amount of debt against it, the terms of the operating agreement, and how much cash flow the property is expected to produce. Two syndications that look similar on paper can have very different values once you account for their debt structure or exit timeline.
Because of this, valuing a syndication interest usually calls for a forensic accountant or business valuation expert. That professional may look at recent sales of similar interests, project future cash flow and discount it to present value, or assess the underlying real estate directly and adjust for debt and other obligations. Because the interest cannot be sold on demand and often comes with transfer restrictions, valuation experts sometimes apply discounts for lack of control and marketability, which can meaningfully lower the number used in your divorce.
On top of the valuation question, most syndication agreements lock up capital for a period of years, sometimes five, seven, or longer, with no mechanism to cash out early. Distributions may happen quarterly or annually, but the bulk of the return usually comes when the property eventually sells or refinances, an event neither spouse controls or can predict with precision. A hard to pin down value combined with no ability to convert it to cash on your own timeline is why syndications tend to be one of the more complicated assets in a Florida divorce, and the same issue comes up with other illiquid alternative investments, including private equity funds, oil and gas partnerships, and hedge fund interests.
How Real Estate Syndications Are Actually Divided
Most syndication operating agreements restrict or flatly prohibit transferring ownership to someone who was not part of the original investment, especially someone who has not been vetted as an accredited investor. In practice, this means the interest itself often cannot be split. What can be divided is its value, and that tends to happen in one of three ways.
Option One: The Investor Spouse Keeps It and Buys Out the Other
The spouse who holds the accredited investor status and the sponsor relationship keeps the syndication interest. The other spouse receives their share of its value through cash, other marital assets, or a combination of both, which can reflect the same discounts a valuation expert applied, so the number is rarely a simple half of a theoretical sale price.
Option Two: A Shared Future Payout Through a Constructive Trust
Sometimes neither spouse wants to force a buyout before the investment becomes liquid, or there are not enough other assets to make one work. In that case, an agreement can create what is known as a constructive trust. The investor spouse continues holding the interest on behalf of both spouses, and when the property eventually sells, the proceeds are divided according to each spouse’s agreed share, net of taxes. In the meantime, any dividends that are distributed can still be distributed to both, with taxes being deducted from the distributions.
Option Three: Attempting a Private Sale
A spouse can try to find a private buyer for their interest, but this path is often the most limited. Syndication agreements frequently include a right of first refusal for the sponsor or other investors, or restrict transfers so heavily that a private sale becomes impractical or outright prohibited.
How Collaborative Divorce Handles Complex Assets Like This
When an asset does not fit neatly into a spreadsheet, the process you use to divide it matters. In a traditional courtroom divorce, a judge who has never heard of a syndication before is asked to rule on how to value and split one, often based on dueling experts and limited time. Collaborative Divorce works differently.
In the Collaborative Process, you and your spouse each have your own lawyer, giving you independent legal advice throughout. Your Collaborative attorneys, along with any financial or other professionals on the team, work solely toward a resolution reached outside of court. If the process ends without resolution, or if either spouse files a contested pleading, the Collaborative professionals must withdraw and cannot go on to represent either of you in litigation, which keeps everyone’s efforts aimed at solving the problem together rather than positioning for a courtroom fight.
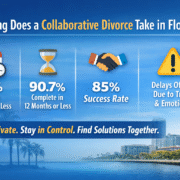
An analysis by Adam B. Cordover and Dr. Randy Heller of Nova Southeastern University, examining nearly 300 Florida Collaborative cases from 2014 to 2024 and published in the Florida Bar Family Law Section Commentator, found an 85 percent overall success rate for the process. For a syndication interest specifically, this means you can bring in a neutral financial professional the two of you agree on, rather than dueling experts, to help design a buyout, a constructive trust, or another resolution tailored to your actual investment documents. No divorce process can guarantee a particular outcome, but Collaborative Divorce gives you more control over how that conversation happens and who is in the room while you have it.
Frequently Asked Questions
Can my spouse force me to sell my real estate syndication interest in our divorce?
Usually not directly. Most syndication agreements restrict who can hold an ownership interest, and a court generally cannot order a sponsor to accept a spouse as a new investor. The interest is typically valued and offset with other assets instead, or handled through an arrangement like a constructive trust.
I’m not the accredited investor. My spouse holds the syndication interest. Am I still entitled to a share?
Often you are entitled to a value of a share. If the investment was made during the marriage, it is generally considered marital property regardless of whose name is on the paperwork, and you are typically entitled to your share of its value, even if you could never invest in the syndication yourself.
How long does it take to value a real estate syndication in a divorce?
It varies. Because there is no public price and the underlying documents can be complex, a valuation expert may need several weeks to a few months to review the operating agreement, financials, and property performance before reaching a supportable number.
Can a prenuptial or postnuptial agreement protect my syndication investment?
Yes. A prenuptial or postnuptial agreement can include a clause that carves out real estate syndications as separate property not requiring valuation or division.
If we agree to a constructive trust, how do I make sure I actually get paid years from now?
The agreement itself is the protection. A well drafted resolution spells out each spouse’s percentage share, how proceeds get calculated and taxed, and what happens if the property is refinanced or sold in stages, so the obligation does not depend on goodwill alone once the investment becomes liquid.
Next Steps
Adam B. Cordover is the managing attorney at Family Diplomacy: A Collaborative Law Firm and co-author of Building a Successful Collaborative Family Law Practice (American Bar Association, 2018). He has guided Tampa Bay and Sarasota area clients through complex financial divorces involving business interests, retirement accounts, and illiquid investments like real estate syndications, and is a former chair of the Research Committee and Ethics and Standards Committee of the International Academy of Collaborative Professionals.
If you are facing divorce and hold an interest in a real estate syndication or similar illiquid investment, the choices you make about valuation and division deserve careful thought, not a rushed courtroom decision.
We invite you to reach out to us at (813) 443-0615. You can also directly schedule a confidential virtual planning meeting or contact Family Diplomacy: A Collaborative Law Firm by clicking the button below to discuss your situation and explore whether Collaborative Divorce is the right path for your family.
When discretion matters, count on us.